.

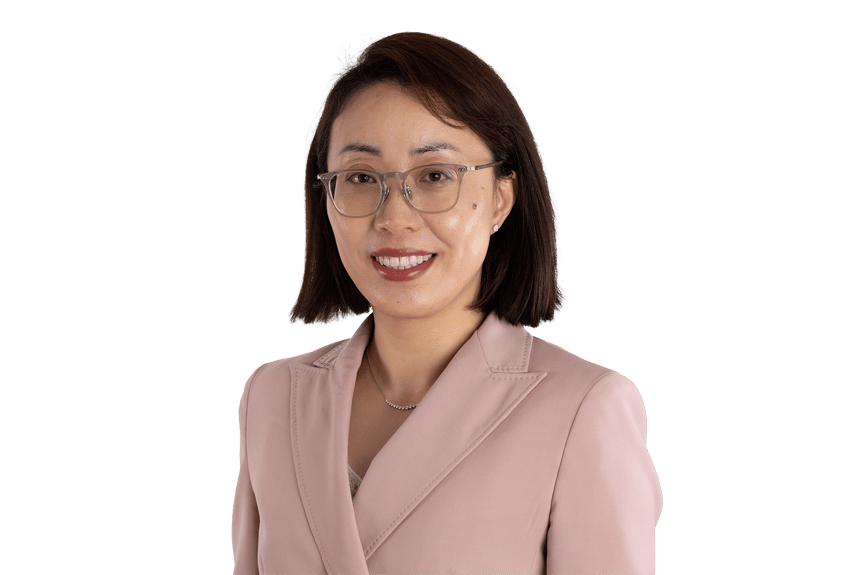
Ting structures and negotiates cross-border M&A, strategic investments, and regulatory compliance matters so that multinational companies and emerging businesses can move capital and technology across U.S.-China borders with legal clarity.

Drawing on more than a decade of U.S. legal practice and nearly a decade of earlier practice in China, Ting Zhou guides clients through some of the most intricate transactional and regulatory challenges at the intersection of these two markets. Whether structuring a billion-dollar greenfield manufacturing investment, negotiating a cross-border M&A transaction, drafting a life sciences licensing agreement, or advising a company through a Committee on Foreign Investment in the United States (CFIUS) review, Ting functions as a primary outside general counsel for many of her clients — a trusted point of contact who coordinates across transactional, regulatory, and litigation disciplines.

Ting's transactional practice centers on domestic and cross-border mergers and acquisitions (M&A), covering both buy-side and sell-side mandates across a range of industries including food & beverages, pharmaceuticals, biotech, clean energy, real estate, and manufacturing. She advises clients on startup formations and early-stage financings — from SAFE agreements and convertible notes through Series A, B, and C rounds — as well as private equity fund formations and secondary transactions. Her clients include Fortune 500 companies, private equity and venture capital firms, entrepreneurs, and scientists.

A significant portion of Ting's practice involves commercial contracts, with a particular focus on life sciences licensing and collaboration transactions between U.S. and Asian counterparties. She has represented global biopharmaceutical companies, U.S. biotechs, and Chinese pharmaceutical companies in negotiating in-licensing, out-licensing, supply, and distribution agreements for technologies spanning oncology, respiratory disease, ophthalmology, and other therapeutic areas. Beyond life sciences, Ting advises U.S. distributors and Chinese suppliers in negotiating manufacturing and supply arrangements for industrial and consumer products.

Ting also advises corporate clients on U.S. regulatory compliance, including CFIUS national security reviews, export controls, U.S. sanctions, and the Commerce Department's connected vehicle rules. She advises clean energy companies on the foreign entity of concern (FEOC) and prohibited foreign entity (PFE) restrictions under the One Big Beautiful Bill Act (OBBBA). She has represented clients ranging from startups to large multinational corporations in navigating these frameworks. On the consumer product side, Ting has guided manufacturers and importers through product recalls, Consumer Product Safety Commission (CPSC) inquiries, and U.S. Customs and Border Protection (CBP) matters, from antidumping and countervailing duty (AD/CVD) enforcement to tariff refund claims.

Select Experience

  • Represented LANXESS in the sale of its Urethane Systems business in the U.S. — as part of a global divestiture — to UBE Corporation of Japan.
  • Represented multiple clean energy and power equipment companies in foreign entity of concern (FEOC) and prohibited foreign entity (PFE) analysis under the One Big Beautiful Bill Act (OBBBA).
  • Represented a Chinese home appliance manufacturer in managing its product recall in the U.S. and Canada, including negotiating with its U.S. distributor on allocation of recall liabilities, preparing responses to the Consumer Product Safety Commission (CPSC), implementing the recall plan, and coordinating with insurance carriers.
  • Represented a furniture importer in protesting CBP’s AD/CVD decisions.

Education

  • Columbia Law School (LL.M., 2015)
    • James Kent Scholar
  • East China University of Politics and Law (LL.B., 2005)

Bar Admissions

  • New York

Accolades

  • New York Metro Super Lawyers®, "Rising Stars," 2026
  • Best Lawyers® Ones to Watch in America, Corporate Law, Mergers and Acquisitions Law, 2026 and 2027

Languages

  • English
  • Mandarin

Insights

Client Alert

Foreign Companies Doing Business in the United States: What the Corporate Transparency Act Still Requires and How to Minimize U.S. Beneficial Ownership Reporting

September 30, 2026

As we previously reported, on August 14, 2026, the Financial Crimes Enforcement Network (“FinCEN”) published a final rule (the “Final Rule”) that made permanent the significant changes to the Corporate Transparency Act (“CTA”) beneficial ownership information (“BOI”) reporting requirements that FinCEN had adopted on an interim basis in March 2025. Under the Final Rule, entities formed in the United States are no longer subject to BOI reporting requirements, and U.S. persons are no longer required to report or provide BOI to reporting companies where they are beneficial owners or company applicants. However, the Final Rule maintains the current framework with respect to foreign entities that qualify as reporting companies. Foreign Reporting Companies Under the Final Rule, a “reporting company” is now strictly limited to an entity (i) formed under the law of a foreign country, and (ii) registered to do business in any U.S. state or tribal jurisdiction by filing a document with a secretary of state or similar office. For example, if a foreign entity registers a branch office by making a qualification or doing-business filing in any U.S. state, the foreign entity, unless otherwise exempt, is a reporting company and must submit a BOI report through FinCEN’s system. FinCEN estimated that the Final Rule’s broadened exemption will reduce the number of entities required to report to approximately 0.06 percent of estimated reporters that were previously required to report under the 2022 regime. While this is a massive reduction in scope, foreign companies with economic ties to the United States must continue to analyze whether they are among the small population of entities that remain obligated to report BOI to FinCEN. Failure to comply can result in significant civil and criminal penalties. Can a Foreign Reporting Company Be Exempt? Registration to do business in the United States does not necessarily trigger a BOI filing. As we previously reported, the CTA and its implementing regulations include several exemptions from the definition of “reporting company” that cover specified categories of entities, including certain securities issuers, banks and other regulated financial institutions, tax-exempt entities, certain large operating companies, and subsidiaries of certain exempt entities. The requirements for these exemptions should be reviewed carefully because several contain conditions that may be particularly relevant to foreign entities that may otherwise be required to file BOI reports. BOI relating to U.S. Persons Now Excluded Even where an entity qualifies as a “reporting company” under the Final Rule and no exemption is available, a reporting company will only be required to report BOI on individuals who are not “U.S. persons”. The term “U.S. person” in the CTA cross-refers to section 7701(a)(30) of the Internal Revenue Code, and generally means a U.S. citizen, U.S. tax resident, or a U.S. partnership, corporation, estate, or trust. The Final Rule provides that: a foreign reporting company is not required to report BOI concerning any U.S. person, whether that U.S. person is a “beneficial owner” or a “company applicant;” and a U.S. person is not required to provide BOI to a foreign reporting company in connection with such U.S. person’s status as a “beneficial owner” or a “company applicant.” How Can Non-U.S. Entities Minimize U.S. Beneficial Ownership Reporting? For foreign reporting companies that are establishing or expanding U.S. operations, entity structure may provide the most straightforward means of minimizing or avoiding a CTA reporting obligation. Under the Final Rule, a “domestic entity,” meaning an entity created by the filing of a document with a secretary of state or similar office under the law of a U.S. state or tribal jurisdiction, is not subject to BOI reporting under the CTA. Accordingly, before filing a foreign qualification for a non-U.S. entity, such entity should consider whether its U.S. operations can instead be conducted through a newly formed U.S. subsidiary. Where appropriate, this structure can eliminate the BOI reporting obligation altogether, regardless of whether the U.S. entity is wholly owned by non-U.S. persons. This does not mean that forming a U.S. subsidiary will always be preferable. Tax, regulatory, licensing, employment, contractual, financing, liability, and other considerations may point in the opposite direction. However, minimizing potential CTA reporting obligations should now be part of the initial corporate structuring analysis for foreign companies doing business in the United States. Global Push for Beneficial Ownership Transparency Minimizing reporting requirements in the United States pursuant to the CTA does not, however, mean that a foreign group’s beneficial ownership information will remain undisclosed worldwide. The CTA’s latest narrowing runs counter to a broader international trend toward greater transparency and verification of beneficial ownership. That trend is reflected in the work of the Financial Action Task Force (“FATF”), an independent intergovernmental body established by the G7 that sets global standards for combating money laundering and terrorist financing. FATF calls on jurisdictions to ensure competent authorities can obtain or access adequate, accurate, and up-to-date information concerning the beneficial ownership and control of companies and other legal entities, and jurisdictions around the world have adopted or strengthened legal frameworks to implement these standards. For example, in the United Kingdom, directors and persons with significant control of UK companies must now verify their identities with UK Companies House under the Economic Crime and Corporate Transparency Act 2023 (see our previous update). In addition, non-UK entities that own or acquire qualifying land or property in the UK are required to register and disclose their beneficial owners on the Register of Overseas Entities. China has likewise adopted a beneficial ownership information filing regime under the Administrative Measures on Beneficial Owner Information, effective November 1, 2024, under which covered entities must report beneficial ownership information to the relevant Chinese authorities. Looking Ahead: U.S. Structuring and CTA Compliance The Final Rule significantly narrows the scope of the CTA’s BOI reporting requirements, but it does not eliminate the need for foreign entities to carefully assess their U.S. operations and organizational structures. Dorsey can assist foreign entities in evaluating whether their U.S. activities may subject them to the CTA’s BOI reporting requirements, including by analyzing U.S. entity structures, state registration requirements, and available CTA exemptions. We will continue to monitor developments relating to the CTA and provide further updates as appropriate.

Articles

“Foreign Entity of Concern” and Its Impact under the Inflation Reduction Act

December 27, 2023

This article is the first in a special series on overseas expansion of Chinese EV and EV battery companies. Why has the definition of “Foreign Entity of Concern” drawn widespread attention? “Foreign entity of concern” (“FEOC”) is a term that frequently appears in many recently enacted laws in the United States, including the CHIPS and Science Act, the Inflation Reduction Act (“IRA”), and the Infrastructure Investment and Jobs Act (the “Jobs Act”). In general, an entity designated as an FEOC and/or any products containing any components or materials produced or processed by an FEOC will be disqualified from being eligible for financial incentives and tax credits under these laws. Therefore, the definition of FEOC holds significant importance for Chinese companies doing business with the U.S., as well as Chinese-owned companies operating within the U.S., particularly in industries such as semiconductor chips, electric vehicles (“EVs”), EV batteries, and their interconnected supply chains. On December 1, 2023, the U.S. Department of Energy (“DOE”) released proposed guidance defining FEOC under the Jobs Act (the "Proposed Guidance"), which holds particular relevance to Internal Revenue Code Section 30D – the Clean Vehicle Tax Credit – as well as the IRA. This comprehensive guidance aims to provide clarity on the definition of FEOC and the specific applications of the FEOC restrictions, carrying substantial implications for Chinese EV and EV battery manufacturers as well as their suppliers and customers. What local content requirements does a clean vehicle need to meet to be qualified for the Section 30D tax credit under the IRA?The IRA, enacted by the Biden-Harris administration in 2022, serves multiple purposes, including economic stimulus, job creation, and the promotion of American domestic manufacturing. A key focus of this law is to amplify the federal government’s financial support to the clean energy sector. To stimulate the sales of clean vehicles in the U.S., the U.S. federal government will provide a consumer tax credit of up to US$7,500 for each purchase of a qualified EV, of which US$3,750 is allocated to an EV meeting the "critical mineral" requirement, and the other US$3,750 is assigned to an EV that meets the "battery component" requirement. How does the FEOC restriction disqualify certain EVs from the coverage of the Section 30D tax credit under the IRA?In April 2023, the Treasury Department and the IRS released guidance on the clean vehicle provisions under the IRA, reaffirming the rule relating to the excluded entity provision of the Section 30D tax credit. Starting in 2024, vehicles containing battery components manufactured or assembled by an FEOC will be ineligible for the $3,750 tax credit. Starting in 2025, vehicles whose batteries contain certain “critical minerals” extracted or processed by an FEOC will also be ineligible for the other $3,750 tax credit. According to this rule, if any supplier to an automotive OEM is identified as an FEOC, the resulting EV containing battery components and/or critical minerals produced or processed by such a supplier will be disqualified from the corresponding tax credit, and the automotive OEM will lose the subsidy advantages. In essence, when selecting suppliers for battery components and/or critical minerals, an automotive OEM or battery manufacturer will be incentivized to choose a non-FEOC supplier. Which suppliers of battery, battery components or critical minerals would be considered FEOCs according to the Proposed Guidance? Within the framework of the IRA, a particularly ambiguous facet of the FEOC definition pertains to foreign entities that are “owned by, controlled by, or subject to the jurisdiction or direction of a government of a foreign country that is a covered nation[1].”  The Proposed Guidance released on December 1 provided a further interpretation of such definition. As per the Proposed Guidance, a foreign entity is an FEOC only if it falls under either scenario A or B below.  A foreign entity is subject to the jurisdiction of a covered nation’s government. Under the Proposed Guidance, a foreign entity is “subject to the jurisdiction” of a covered nation’s government if: (i) the foreign entity is incorporated or domiciled in, or has its principal place of business in, a covered nation; or (ii) with respect to the critical minerals, components, or materials of a given battery, the foreign entity engages in the extraction, processing, or recycling of such critical minerals, the manufacturing or assembly of such components, or the processing of such materials, in a covered nation. A foreign entity is owned by, controlled by, or subject to the direction of a covered nation’s government.Under the Proposed Guidance, an entity is “owned by, controlled by, or subject to the direction” of another entity (including the government of a covered nation) if: (i) 25% or more of the entity's board seats, voting rights, or equity interest are cumulatively held by that other entity, whether directly or indirectly via one or more intermediate entities; or (ii) with respect to the critical minerals, battery components, or battery materials of a given battery, the entity has entered into a licensing arrangement or other contract with another entity (a contractor) that entitles that other entity to exercise effective control over the extraction, processing, recycling, manufacturing, or assembly (collectively, “production”) of the critical minerals, battery components, or battery materials that would be attributed to the entity. Note that as per the definition of “foreign entity,” a U.S. subsidiary of a non-U.S. company is also deemed as a “foreign entity”, thus it could be considered an FEOC if it falls under either A or B above.  However, a subsidiary of an FEOC is not automatically considered as an FEOC unless the subsidiary itself falls under either scenario A or B above. “Government of a [covered nation]” is defined to include even individual government representatives. Which individuals would be counted as “government of a [covered nation]”?The DOE proposed to interpret “government of a foreign country” to mean: (i) a national or subnational government of a foreign country; (ii) an agency or instrumentality of a national or subnational government of a foreign country; (iii) a dominant or ruling political party of a foreign country; or (iv) a current or former senior foreign political figure. The DOE further explains that “Senior Foreign Political Figure” in (iv) of the definition means: (a) a senior official, either in the executive, legislative, administrative, military, or judicial branches of a foreign government (whether elected or not), or of a dominant or ruling foreign political party, and (b) an immediate family member (spouse, parent, sibling, child, or a spouse’s parent and sibling) of any individual described in (a). The DOE also provided explanations of the above interpretation specifically regarding China. For more details, please refer to Section C of the proposed interpretive rules released by the DOE. How can a Chinese supplier of battery, battery components or critical minerals determine whether their products may affect their clients’, i.e. automotive OEMs’, FEOC compliance? Based on the Proposed Guidance and the examples of indirect control delineated by the DOE, in the table below, we analyzed different types of Chinese EV and EV battery suppliers under the definition of FEOC.  Please note that the terms of “state-owned enterprise”, “enterprise with non-controlling state ownership” and “non-state-owned company” in the table below carry the meanings commonly used in the Chinese context. In this context, “state-owned” denotes equity ownership equal to or exceeding 50% held by the state; "non-controlling state ownership" means equity ownership between 0% to 50% held by the state; and "non-state-owned company" refers to a company without any state ownership. However, it is crucial to be mindful that the definition of “government of a [covered nation]” under the Proposed Guidance is very broad. For example, as discussed in paragraph 5 above, certain individuals may be deemed as “government of a [covered nation]” according to the Proposed Guidance. A company controlled by such individuals may be deemed as controlled by the “government of a [covered nation],” and thus becomes an FEOC. Furthermore, for the purpose of determining a company’s FEOC status, it is imperative not only to review its direct and indirect equity ownership but also to delve into factors such as the board seats, voting rights, and contract arrangements. For example, certain type of companies in the table below may not be considered as an FEOC based on its equity ownership alone; however, it could still be considered as an FEOC if more than 25% of its board members are individuals falling within the extensive category of “Senior Foreign Political Figure”. Types of Companies FEOC Status 1. Chinese state-owned enterprise (incorporated in China), and its wholly-owned subsidiaries FEOC, since it is directly or indirectly controlled by Chinese government through majority equity ownership. 2. Equity joint venture (incorporated, domiciled or with its principle place of business outside of China, the “JV”) with its controlling stake held by a Chinese state-owned enterprise (the “Parent”) If the Parent owns 25% or more equity or voting rights in JV, the JV is likely to be deemed as an FEOC. If the Parent owns less than 25% equity or voting rights in the JV, andif 25% or more of the board members of the JV are CCP members or current/former Senior Foreign Political Figures, the JV may be deemed as an FEOC; if fewer than 25% of the board members of the JV are CCP members or current/former Senior Foreign Political Figures, but 25% or more of the board members of the Parent are CCP members or current/former Senior Foreign Political Figures, the Proposed Guidance does not offer a clear answer as to whether the JV is an FEOC. It is possible that indirect foreign government control via board members of the Parent may be extended to the JV, potentially resulting in the JV to be deemed as an FEOC. As the DOE is currently soliciting public comments to the Proposed Guidance, this issue may be further clarified in the final version of the rules established in the Proposed Guidance. 3. JV with its controlling stake held by an enterprise with non-controlling state ownership (the “Parent”) If the state ownership or voting rights in the Parent amounts to 25% or more, the JV is likely to be deemed an FEOC. If the state ownership or voting rights in the Parent amount to less than 25%, andif 25% or more of board members of the JV are CCP members or current/former Senior Foreign Political Figures, the JV may be deemed as an FEOC; if fewer than 25% of the board members of the JV are CCP members or current/former Senior Foreign Political Figures, but 25% or more of the board members of the Parent are CCP members or current/former Senior Foreign Political Figures, the Proposed Guidance does not offer a clear answer as to whether the JV is an FEOC. It is possible that indirect Chinese government control via board members of the Parent may be extended to the JV, potentially resulting in the JV to be deemed as an FEOC; if each of the JV and the Parent has less than 25% board members as CCP members or current/former Senior Foreign Political Figures, the JV is not likely to be deemed as an FEOC. 4. JV with non-controlling equity interest held by an enterprise with non-controlling state ownership (the “Parent”) If, by multiplying the ownership percentages (by equity or by voting rights) at both the JV level and the Parent level, the resulting state ownership (by equity or by voting rights) in the JV is no less than 25%, the JV may be deemed as an FEOC. If, by multiplying the ownership percentages (by equity or by voting rights) at both the JV level and the Parent level, the resulting state ownership (by equity or by voting rights) in the JV is less than 25%, andif 25% or more of board members of the JV are CCP members or current/former Senior Foreign Political Figures, the JV may be deemed as an FEOC; if fewer than 25% of the board members of the JV are CCP members or current/former Senior Foreign Political Figures, but 25% or more of the board members of the Parent are CCP members or current/former Senior Foreign Political Figures, the Proposed Guidance does not offer a clear answer as to whether the JV is an FEOC. It is possible that indirect foreign government control via board members of the Parent may be extended to the JV, potentially resulting in the JV to be deemed as an FEOC; if each of the JV and the Parent has less than 25% board members as CCP members or current/former Senior Foreign Political Figures, then the JV is not likely to be deemed as an FEOC. 5. Non-state-owned company incorporated in China FEOC, since it is incorporated in China and subject to the jurisdiction of the Chinese government. 6. Wholly-owned subsidiary (incorporated, domiciled or with its principal place of business outside of China, the “Subsidiary”) of a non-state-owned company that is incorporated in China (the “Parent”) Although the Subsidiary is wholly owned by an FEOC, the Subsidiary is not automatically considered as an FEOC. Since there is no state ownership in such Subsidiary, the determination of whether the Subsidiary is an FEOC depends on the composition of the board of the Subsidiary and the board of the Parent.If 25% or more of board members of the Subsidiary are CCP members or current/former Senior Foreign Political Figures, the Subsidiary may be deemed as an FEOC. If fewer than 25% of the board members of the Subsidiary are CCP Members or current/former Senior Foreign Political Figures, but the Parent’ board comprises 25% or more CCP Members or current/former Senior Foreign Political Figures, the Proposed Guidance does not offer a clear answer as to whether the Subsidiary is an FEOC. It is possible that indirect foreign government control via board members of the Parent may be extended to the Subsidiary, potentially resulting in the Subsidiary to be deemed as an FEOC. Given that the Subsidiary represents the majority scenario of legal entities used by Chinese EV and EV battery companies in their investments in the United States, the final version of the Proposed Guidance to be published after public comments being solicited may include revised provisions or further clarifications on this issue. If each of the Subsidiary and the Parent has less than 25% board members as CCP members or current/former Senior Foreign Political Figures, the Subsidiary is not likely to be deemed as an FEOC. The determination of FEOC status is extremely complex, requiring a careful facts-based review on a case-by-case basis. Should you have any inquiries regarding the determination of FEOC status of your company, please feel free to reach out to the authors of this article for further consultation. [1] A covered nation refers to any of (A) the Democratic People’s Republic of North Korea; (B) the People’s Republic of China; (C) the Russian Federation; and (D) the Islamic Republic of Iran.  For the purpose of this article, we only discuss the rules relevant to China.

Firm Highlights

Insights

Minnesota Consumer-Fraud Enforcement: Disclaimers Won’t Cure Deception, and Penalties Can Add Up

Misleading advertising claims can lead to costly consequences. In State of Minnesota ex rel. Ellison v. Wall & Associates, Inc., No. A25-2064, 2026 WL 3118291 (Minn. App. Oct. 19, 2026), the Minnesota Court of Appeals recently affirmed a bench trial verdict against a tax-relief company and two executives for violations of the Minnesota Consumer Fraud Act (“MCFA”) and the Minnesota Deceptive Trade Practices Act (“MDTPA”). The decision, which affirmed a substantial restitution and civil penalty judgment, underscores the broad power of the Minnesota Attorney General to act against deceptive sales practices. The decision also offers practical lessons for businesses seeking to reduce liability risks in consumer-facing communications. Background Wall & Associates (“W&A”), a Virginia-based tax-relief company, marketed assistance to taxpayers seeking relief from outstanding federal and state tax liabilities, often with offers in compromise—agreements to settle tax liabilities for less than the amount owed. In its extensive advertising campaigns, W&A represented that its average client received a 90% reduction in their tax debt, that it was a local company with Minnesota offices, that it provided legal services, and that it would “Solve ALL Tax Problems.” In reality, W&A’s promises bore little resemblance to what many clients received. Most of W&A’s clients saw just a 9.5% reduction in federal tax debt and 1.2% in state tax debt. W&A had no permanent Minnesota offices. And W&A provided neither legal representation nor assistance with filing tax returns—those services required referrals to separate firms for an additional fee. All the while, W&A clients paid upfront and recurring fees, including during periods when W&A did no work on their cases. Minnesota Attorney General Keith Ellison sued W&A, its founder and owner Ernest Kenneth Wall, and its president and CEO Patrick Mark Yates, alleging violations of, among other laws, the MCFA and the MDTPA. Following a 12-day bench trial, the district court determined that W&A violated the MCFA and MDTPA through its false and embellished advertising. The district court also held Wall and Yates individually liable for those violations because they directed, participated in, and acquiesced in the violations. The district court ordered injunctive relief, $2.7 million in restitution (with Wall and Yates jointly and severally liable for $1.3 million), and civil penalties of $786,517 against W&A, $415,500 against Wall, and $207,750 against Yates. The district court also awarded over $2.5 million in attorneys’ fees and costs to the state. W&A, Wall, and Yates appealed to the Minnesota Court of Appeals, which affirmed the district court’s decision on October 19, 2026. Although W&A, Wall, and Yates challenged the judgment on numerous grounds, several highlights of the decision provide important takeaways for consumer-facing businesses. Individual Reliance Is Not Required for Statutory Liability W&A argued that Attorney General Ellison had to prove a causal nexus between each violation of the MCFA and MDTPA and the injury to a particular consumer to establish liability. In W&A’s view, this required proof that each injured consumer had personally relied on W&A’s false representation. The Court of Appeals rejected this argument based on the MCFA’s and MDTPA’s plain language, which requires no proof of actual deception or confusion by consumers. The Court of Appeals finally pointed to the Minnesota Supreme Court’s decision in State v. Minnesota School of Business, Inc., which held that when a defendant’s misrepresentations are directed at and affected “a broad group of consumers, proof of direct individual reliance is not required to establish a causal nexus between MCFA violations and the harm suffered by consumers.” 935 N.W.2d 124, 135 (Minn. 2019). The Court of Appeals affirmed, however, that a causal nexus is necessary to support an award of damages under the MCFA and MDTPA. In making that determination, district courts look to various factors, including whether the misrepresentations were “longstanding, pervasive, and widespread in communications directed to consumers,” whether the seller intended and understood that consumers would rely on the misrepresentations, and whether the information was of a kind on which consumers would typically rely. The Court of Appeals’ decision continues Minnesota School of Business’s broad interpretation of liability under the MCFA and the MDTPA. Coordinated marketing campaigns to a “broad group of consumers” may expose businesses to MCFA and MDTPA liability without customer-by-customer proof of injury. That said, a causal nexus remains an element of an MCFA and MDTPA claim, and businesses involved in litigation should build a clear record at trial and on appeal showing how each of the relevant factors bears on the causal-nexus inquiry. Contractual Disclaimers Are Not an Automatic Defense to a Misleading Pitch W&A next argued that disclaimers in its client contracts prevented consumers from claiming they had been misled by its advertising. Reiterating that individual reliance is not required under the MCFA and MDTPA, the Court of Appeals held that a contractual disclaimer does not necessarily defeat a claim based on a conflicting oral representation. And on the facts of this case, the Court of Appeals agreed with the district court that W&A’s contractual disclaimers were insufficient given the extensive misrepresentations by W&A and the unequal bargaining power between it and its customers. This holding confirms that contractual disclaimers are not a cure-all for misleading advertising or sales practices. Businesses should review the entire customer journey, including pre-contract representations, as those representations may survive a contractual disclaimer to the contrary. And if faced with litigation, businesses should build a strong record, both at trial and on appeal, showing why any disclaimer is effective in context. The State Has Broad Authority to Seek Restitution W&A also challenged Attorney General Ellison’s authority to seek restitution under the state’s parens patriae authority to protect residents’ collective interests, arguing that injury to only 228 Minnesotans did not affect a sufficiently substantial segment of the population. The Court of Appeals rejected a simple headcount approach, instead explaining that the state had a legitimate interest in protecting residents’ economic well-being as a whole. In any event, the Court of Appeals held that if restitution was not appropriate under the state’s parens patriae authority, then it would still be appropriate under the Attorney General’s enforcement powers under Minn. Stat. § 8.31. The decision reinforces that the broader and more sustained the deceptive advertising, the stronger the case for restitution to protect Minnesotans’ economic interests. Civil Penalties Accrue Per Violation, Not Per Defendant The Court of Appeals finally rejected W&A’s claim that the Attorney General’s enforcement powers under Minn. Stat. § 8.31 permit only civil penalties of up to $25,000 for each defendant. Rather, the Court of Appeals explained that penalties are limited to $25,000 per violation. Multiple violations can therefore produce substantially greater penalties. The Court of Appeals also rejected the argument that restitution made penalties unnecessary: repaying consumers does not eliminate the need to address gains from deceptive conduct and deter future violations. Final Takeaways Align every consumer-facing communication. Broad and extensive marketing campaigns can expose businesses to stronger enforcement standards under the MCFA and MDTPA, making it critical that consumer communications remain accurate and consistent from the first advertisement through the final sale. Plan for layered enforcement exposure. Penalties under the MCFA and MDTPA can add up quickly: W&A, Wall, and Yates ultimately faced more than $6 million in civil penalties, restitution, and attorneys’ fees. The decision continues a line of Minnesota cases recognizing the Attorney General’s broad consumer-protection authority. Details matter. Although the Attorney General’s enforcement power is broad, it is not boundless. As the Court of Appeals explained, issues of causation, the effectiveness of contractual disclaimers, and the availability of restitution and civil penalties all turn on the specific facts of the case. Effective advocacy at trial and on appeal is critical to developing the facts relevant to liability and damages.